
How a Letter of Credit Works in International Trade
Trade between two businesses that have never met carries a familiar problem. The buyer does not want to pay before the goods ship, and the seller does not want to ship before the money is secure. For centuries the answer has been to replace trust in the counterparty with trust in a bank. The letter of credit is that instrument, and it remains one of the most widely used tools in international trade in 2026.
This guide explains who is involved, how the money actually moves, what the credit costs, how it differs from a bank guarantee, and how to avoid the document errors that cause most disputes. If a shipment is held up by a payment issue rather than the credit itself, our guide on demurrage fees explains the cost that builds while cargo waits.
Who Is Involved in a Letter of Credit
Four parties usually matter, and a fifth appears in many transactions.
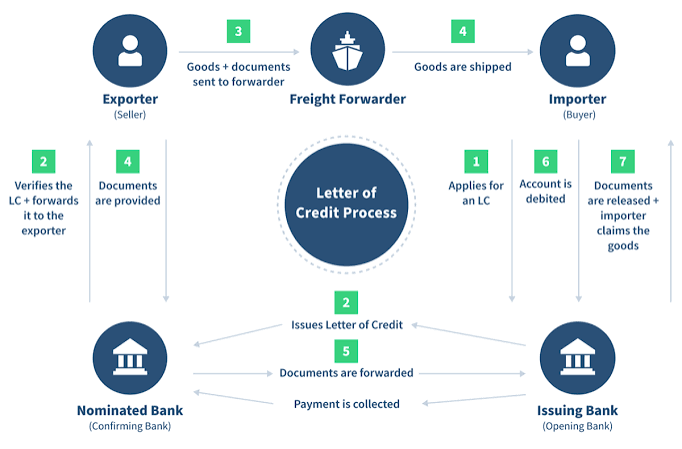
The applicant is the buyer, the party who asks its bank to issue the credit. The issuing bank is the buyer's bank, and it takes on the obligation to pay if the documents are in order. The beneficiary is the seller, the party entitled to payment. The advising bank is a bank in the seller's country that authenticates the credit and passes it to the seller.
The fifth party is the confirming bank. When the seller does not want to rely on the credit standing of a bank in the buyer's country, it can ask a bank in its own market to add its confirmation. That bank then pays the seller directly if the documents comply, and it looks to the issuing bank for reimbursement. Confirmation turns a distant promise into a local one, and it is the reason a small exporter can trade confidently with a buyer on the other side of the world.
The rules that govern the whole arrangement are published by the International Chamber of Commerce in its Uniform Customs and Practice for Documentary Credits, explained at ICC. Most credits issued in 2026 state UCP 600, and that single reference decides how banks interpret the documents.
The Basic Flow Step by Step
A letter of credit looks complicated from the outside, but the sequence is mechanical.
- The buyer and seller agree the contract and confirm that payment will run through a letter of credit.
- The buyer applies to its bank, which issues the credit in favour of the seller on the agreed terms.
- The advising bank authenticates the credit and delivers it to the seller, adding confirmation if required.
- The seller ships the goods and collects the documents named in the credit, such as the bill of lading, the commercial invoice, and the packing list.
- The seller presents the documents to its bank within the stated period.
- The bank examines the documents against the credit. If they match, payment follows. If they do not, the bank may refuse.
- The documents travel to the issuing bank, which reimburses the paying bank and releases the documents to the buyer so the buyer can collect the goods.
The important point sits in the last steps. Banks deal in documents, not in goods. A bank does not inspect the cargo, and it does not care whether the goods are excellent or poor. It checks whether the paperwork matches the credit, and that is the entire test.
Why Businesses Use a Letter of Credit
The instrument balances risk. The seller gains a bank commitment instead of a promise from a stranger, which makes payment far more likely. The buyer gains control, because the documents that release the goods are held until the bank is satisfied.
It also widens who can trade. A supplier who would refuse open account terms for a first order will often accept a confirmed credit, because the risk shifts to banks. That opens new markets and new suppliers.
Official analysis supports the value of this kind of financing. The World Bank has repeatedly documented the trade finance gap that constrains small exporters at World Bank, and the practical effect of a documentary credit is to reduce that gap for transactions that would otherwise never happen.
The trade off is friction. A credit adds documents, bank charges, and a strict timetable. It suits a high value shipment between parties who do not yet trust each other, and it is often unnecessary once a trading relationship is established.
The Main Types of Letter of Credit
Different transactions call for different structures, and the name tells you how each one behaves.
| Type | How it works | Best suited to |
|---|---|---|
| Irrevocable | Cannot be changed without all parties agreeing | Most modern credits |
| Confirmed | A second bank adds its own payment promise | Sellers facing country risk |
| Sight | Payment on presentation of complying documents | Sellers who want money quickly |
| Usance or time | Payment at a stated future date | Buyers who need time to sell goods |
| Transferable | The beneficiary can pass the credit to a supplier | Traders in the middle of a chain |
| Standby | Payable only if the buyer fails to perform | Guarantee style protection |
| Revocable | Can be amended or cancelled by the issuing bank | Rare, weak protection |
In practice, almost every credit issued today is irrevocable, because a revocable credit offers the seller very little. The choice usually comes down to whether the seller needs confirmation, and whether payment is on sight or at a future date.
Documents, Discrepancies, and Why They Cause Most Disputes
The documents are the payment trigger, so an error in them is an error in the payment.
The typical pack includes a commercial invoice, a bill of lading or equivalent transport document, a packing list, an insurance certificate where the terms require it, and any inspection or quality certificate named in the credit. A common cause of refusal is a mismatch between one document and another, such as a shipment date that does not align with the credit or a description of goods worded differently from the invoice.
The rules are strict for a reason. When a document does not match the credit, banks call it a discrepancy, and the issuing bank has the right to refuse. In practice many discrepancies are waived by the buyer, but waiving one takes time and can delay payment by days. Almost all of that risk is avoidable by checking the credit terms before shipping, not after.
What a Letter of Credit Costs
Costs are charged as a percentage of the credit value plus a schedule of fixed fees, so the total depends on the amount and the duration.
| Charge | Typical basis in 2026 |
|---|---|
| Issuing commission | About 0.1 to 1 percent of value per quarter |
| Confirmation | About 0.1 to 0.5 percent of value per quarter |
| Amendment | A fixed fee per amendment, plus any increase in commission |
| Document examination | A fixed fee per presentation |
| Discrepancy fee | A fixed penalty per set of discrepant documents |
| Courier and handling | A fixed fee per set |
Two patterns matter for planning. A credit that runs for two quarters costs roughly twice the quarterly commission, so duration is as important as value. And confirmation is only as expensive as the risk the confirming bank takes on, which is why it can be cheap for one corridor and costly for another.
Is a Letter of Credit a Loan?
No. A letter of credit is a payment guarantee, and it does not put money in the buyer's hands. The buyer must fund the payment when the documents comply, either from its own balance or from a separate facility.
This is the most common confusion in trade finance, and it matters for accounting and for cash planning. Because a credit is a contingent obligation, it usually sits off the balance sheet as a commitment rather than on it as debt. A bank guarantee works in a similar way, though it is drawn on only when a party fails to perform rather than when the seller delivers documents.
Some credits are structured as usance credits, where the buyer pays at a future date. Even then, the seller may discount the receivable with its bank to receive funds early, and that discounting is a separate financing arrangement rather than part of the credit itself.
Why the Payment Rails Still Matter
A credit secures the obligation to pay, but it does not by itself move money quickly. Once the documents comply, the payment still has to travel from bank to bank, which means cut off times, correspondent hops, and the same delays that afflict any international wire. That is why businesses that trade on documentary credits often pair the guarantee with a faster settlement rail for the payment that follows.
DapsyPay runs on conventional international transfer rails such as SEPA and ACH, so once a payment is due it moves fast and lands directly in a named bank account. There are no limits on the amount, which suits the large sums that trade finance generates, and pricing is transparent instead of hidden inside the exchange rate. For an importer releasing a container or a buyer settling a sight credit, the credit provides the security and the platform provides the speed.
The mainstream alternatives each solve part of the problem. Wise handles smaller transfers well, though its cost rises with the amount. OFX is built for larger payments with fixed quotes, but delivery still follows banking hours. The platform is positioned for the business that needs both scale and speed on the settlement leg, without paying a premium for the wait.
Common Mistakes With Letters of Credit
- Agreeing the credit terms verbally and leaving key wording out of the contract.
- Shipping before checking the credit terms, then discovering a document cannot be produced.
- Missing the presentation deadline, which can invalidate the bank's obligation.
- Assuming the bank inspects the goods, when it only examines documents.
- Treating the credit as a loan and failing to fund the payment when documents comply.
- Skipping confirmation on a corridor with genuine country or bank risk.
- Forgetting that each amendment costs money and time, then amending repeatedly.
Frequently Asked Questions
Conclusion
A letter of credit replaces trust between strangers with an undertaking from a bank. The buyer's bank promises to pay, a confirming bank can make that promise local, and the trigger is a set of documents that match the credit exactly. It is a guarantee rather than a loan, it costs a percentage of value over time, and it remains one of the most reliable ways to trade safely across borders in 2026. Get the terms right before shipping, watch the presentation deadline, and the instrument works as intended.
For the wider picture, our guide on tracing a wire transfer explains what to do when the settlement leg goes wrong, our post on working capital shows how to fund the payment itself, our explainer on demurrage covers the cost of cargo that waits at port, and our guide to choosing between the main transfer networks compares another route for cross-border settlement. Choose the security you need, then move the money on a rail that keeps pace.
Move Trade Payments Faster
Fast, transparent cross-border payments on conventional rails, built for large trade sums with no limits.
Visit dapsypay.com