
How Much Does Escrow Cost
Escrow usually costs between 0.5 percent and 5 percent of the transaction value, and on very small deals a flat minimum fee of around 25 to 50 dollars applies instead. Card based escrow and marketplace escrow sit at the higher end, while direct escrow providers on large transactions sit near the lower end. The buyer, the seller or both may pay it depending on the agreement. Compared with losing an entire deposit, escrow is often inexpensive, but it is not free protection. (88 words)
What an Escrow Fee Is Actually Paying For
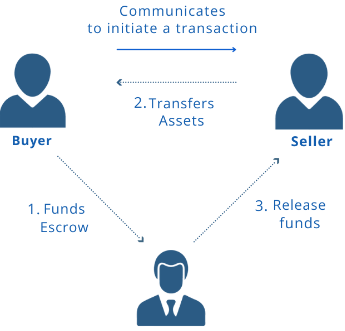
Escrow is a neutral third party that holds money until agreed conditions are met. The fee pays for that neutrality, and it covers four real costs.
- Custody. The escrow provider holds your funds in a controlled account for days or months.
- Verification. In regulated escrow, the provider runs checks on both parties, which is part of the anti money laundering duty.
- Release administration. Someone has to confirm that the goods shipped, arrived or matched the specification before money moves.
- Dispute handling. If the two sides disagree, the escrow provider investigates instead of the money simply vanishing.
That is why escrow is a different product from a payment platform. A payment platform moves money efficiently. Escrow adds a referee, and referees are paid for their time. The United States Federal Trade Commission explains the general principle behind avoiding fraud in high value purchases, and escrow is essentially that principle with an institution in the middle.
How Escrow Fees Are Calculated
Escrow pricing looks simple and is not. Most providers combine a percentage with a minimum.
| Deal size | Typical structure | Effective cost |
|---|---|---|
| Under 1,000 dollars | Flat minimum fee | Often 25 to 50 dollars per side |
| 1,000 to 50,000 dollars | Percentage of the transaction | Roughly 1 percent to 5 percent |
| 50,000 to 500,000 dollars | Lower percentage, sometimes negotiated | Roughly 0.5 percent to 2 percent |
| Above 500,000 dollars | Negotiated fee or a capped schedule | Frequently under 1 percent |
Two extra charges appear often. A card fee applies when you fund escrow with a credit or debit card, because the card scheme charges the provider. A currency conversion spread applies when the escrow is held in one currency and paid out in another, and it can quietly outweigh the visible fee.
The practical rule is to ask for an all in number in the currency the seller will receive. The visible percentage is only half the story.
Typical Escrow Costs by Use Case
The same percentage lands very differently depending on what you are buying.
- Marketplace escrow for imported goods. Usually the higher end, because volumes are smaller and disputes are more common. Expect a percentage fee plus a possible payment processing charge.
- Property and high value assets. Often the lowest rate in percentage terms, because the sums are large and the process is well established.
- Freelance and service contracts. Sometimes built into a platform subscription rather than charged per deal.
- Customs and clearance escrow. Rare outside specialist trade finance, but it appears in some letter of credit arrangements.
If you are comparing escrow with a plain transfer for a straightforward order from an established supplier, the gap can look hard to justify. The comparison changes when the supplier is new, the sum is large or the goods are custom made and unsellable elsewhere. In those cases escrow is not a fee for moving money. It is a fee for not losing it. You can see how regulated providers present the service on the Escrow.com site, which also shows how fees scale with value.
Who Pays the Escrow Fee
This is negotiable, and it is worth negotiating early.
- Buyer pays. Common, because the buyer is the one buying protection.
- Seller pays. Appears when the seller wants to win a competitive order and absorb the friction.
- Split. A frequent compromise, especially in cross-border trade.
- Both pay separately. Some marketplaces charge each side a smaller fee, which is why a buyer quote and a seller payout can both look reduced.
Whatever you agree, write it into the agreement before money moves. Ambiguity about who pays becomes a dispute at exactly the moment you need cooperation.
Escrow Cost Versus the Cost of Losing Your Money
Escrow is easiest to judge against the alternative outcome, not against a free transfer.
Imagine a 40,000 dollar order. A 1.5 percent escrow fee is 600 dollars. If the supplier fails to deliver and you recover nothing because you paid a stranger directly, the loss is 40,000 dollars, plus the disruption to your business and your cash flow. On that comparison, 600 dollars is not a cost. It is insurance. The United States Consumer Financial Protection Bureau offers practical guidance on protecting money in transactions, and the theme is consistent: put a controlled process between you and an unverified counterparty when the sum matters.
The counter argument is real too. If you pay escrow on every order, including repeat orders from a supplier you have used for years, the fees become a permanent tax on a relationship that does not need protecting. Match the protection to the risk.
Cheaper Alternatives to Paid Escrow
Escrow is not the only way to reduce risk. Several lower cost structures achieve most of the same benefit.
- Staged payments. Pay a deposit, then pay the balance against production photos or a shipping document. This is the most common and cheapest form of protection.
- Inspection before final payment. Pay for a third party inspection and release the balance only after it passes.
- Trade Assurance style platform cover. Some marketplaces bundle limited buyer protection into the transaction for free, with restrictions on how and when you can claim.
- Letter of credit. A bank guarantees payment against documents, which is strong but slow and fee heavy.
- A traceable transfer plus verification. Confirm the beneficiary is the real business, then pay through a route you can recall if things go wrong.
Staged payments are where most importers land, because they cost nothing extra and still split the risk. The discipline is in the schedule. The deposit must be small enough to survive a total loss, and the balance must be timed to a document you can verify.
The structure of the transfer matters as much as the structure of the protection, so it helps to know how each route behaves. Our guide on What Is a Wise Transfer explains how mid market transfers price and settle, and our guide on what to do when a deal collapses, What to Do When a Supplier Disappears After You Pay, explains recall and chargeback routes when protection was never put in place. If you are weighing stablecoins as an alternative rail for settlement, start with the fundamentals in What Is a Blockchain.
Moving the Funds Without Paying Twice
Here is the mistake that erodes the value of any protection: paying over the odds to move money into and out of the escrow arrangement.
Every extra transfer is another fee, another exchange rate and another chance of a deduction. If you fund an escrow account in one currency, hold it in a second and release it in a third, the conversion spreads can cost more than the escrow fee itself. That is why the payment rail underneath the arrangement deserves the same attention as the protection on top of it.
DapsyPay is built for exactly that layer. It runs on conventional international rails such as SEPA and ACH, so funds reach a named beneficiary bank account rather than a chain of intermediaries, and there are no limits on the amount you can send. The fee and exchange rate are shown before you confirm, which means you can budget the true all in cost of a staged payment instead of discovering it after release. For importers and business owners moving several supplier payments a month, the bulk sending design keeps each instruction clean and traceable, so the money you meant to protect is not quietly reduced by the route it travelled.
If your counterparty is a hospital or clinic rather than a factory, the payment mechanics are similar but the timing is more sensitive. Can I Pay a Hospital Abroad Directly covers how those deposits are structured and protected.
Common Mistakes When Paying for Escrow
- Only comparing the visible percentage. Card fees and conversion spreads change the real cost.
- Escrowing every order. Protection has a price, and repeat suppliers rarely justify it.
- Not agreeing who pays. An unspoken assumption becomes a dispute at release.
- Ignoring release conditions. If the wording is vague, the provider decides when the money moves.
- Funding escrow with a card on a large sum. It is convenient and expensive.
- Skipping supplier verification because escrow exists. Escrow protects the transaction, not against every fraud pattern.
- Leaving the funds in a foreign currency for weeks. Currency movement can outweigh the fee.
Frequently Asked Questions
Conclusion
Escrow costs somewhere between 0.5 percent and 5 percent, with flat minimums on small deals and conversion spreads that sit outside the headline fee. It is a fee for a referee, and referees are worth paying for when the outcome is genuinely uncertain.
The smart approach is layered. Use free structures such as staged payments and inspection for ordinary orders, use paid escrow when the risk justifies it, and always move the money on a route with no limits, a visible rate and a named beneficiary, so protection does not get eaten by the cost of the transfer itself.
Protect the Deal Without Paying Twice
Fund staged and protected payments on conventional rails with no limits, a transparent fee, and direct delivery into the named beneficiary bank account.
Visit dapsypay.com