
How to Add Multi-Currency Checkout to Your Cross-Border Ecommerce Store
Multi-currency checkout lets a shopper see prices, pay, and be charged in their own currency, using payment methods they already trust. Setting it up means choosing a payment service provider that supports local currency pricing and local payment methods, configuring price display and rounding rules, and deciding who carries the currency conversion cost. Stores that show local prices and familiar payment methods generally complete more international orders than stores that force every buyer into a single currency. The configuration is straightforward. The commercial decision behind it is the part that changes your margin.
What Multi-Currency Checkout Actually Means
A multi-currency checkout is not one feature. It is a set of decisions about how money is presented, collected, and converted.
At the simplest level, it means a customer in Germany can see prices in euros, a customer in the United Kingdom can see prices in pounds, and a customer in Nigeria can see prices in dollars or naira. Behind that display sit several separate questions. Which currency is the price held in? Who performs the conversion? Which payment methods are offered in each country? And what happens to the money after the customer pays?
Most stores that sell internationally start with a single currency, usually dollars, and a single payment method, usually card. That works until it does not. Buyers who see an unfamiliar currency have to calculate the total themselves, and the number they arrive at is rarely the number their bank charges. That gap is where abandoned carts come from.
Why Local Currency Pricing Changes Conversion
Buyers do not abandon a checkout because they dislike the product. They abandon it because something in the payment step felt uncertain.
A shopper who sees a price in their own currency knows the exact amount leaving their account. A shopper who sees a foreign currency has to guess, and the guess is usually wrong, because the bank adds its own conversion on top. Baymard Institute research on cart abandonment continues to show payment and cost uncertainty among the leading reasons shoppers leave a checkout, and the extra doubt created by currency conversion sits directly in that category. Baymard Institute maintains one of the most widely cited datasets on why online shoppers abandon carts, and cost uncertainty at the payment step is consistently among the top reasons.
Local currency pricing removes that doubt. It also removes a second, subtler problem: trust. A payment page that shows a familiar currency and a familiar payment method looks like a local store. A payment page that shows an unfamiliar currency and only one card option looks like a foreign website, and foreign websites get abandoned at a higher rate.
The practical outcome is simple. Displaying local currency and offering local payment methods usually converts better than optimising the product page again.
How a Cross-Border Payment Moves After the Customer Pays
Understanding the money flow makes the configuration decisions easier.
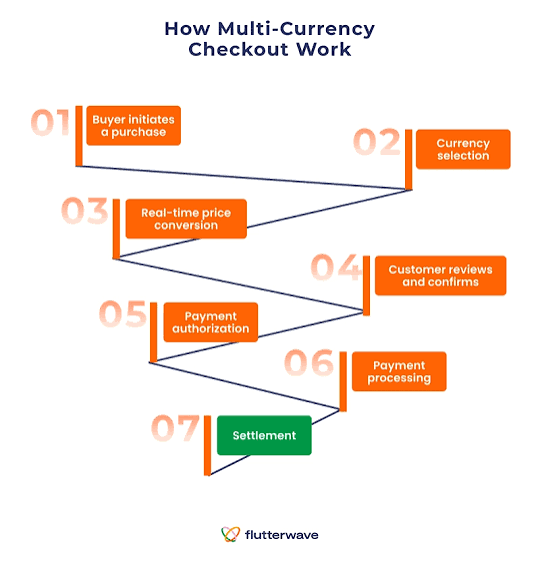
When a customer pays, the payment service provider collects the funds, applies its own conversion if the currency differs from your settlement currency, deducts its fees, and settles the balance into your account. That settlement can take a few days, and the exchange rate applied at settlement is usually not the rate shown to the customer at checkout.
That gap matters. If you show a buyer a converted price but settle at a later, less favourable rate, the difference comes out of your margin. Stripe documents how currency conversion, settlement timing, and cross-border card fees interact in a global checkout, and reading that documentation is a useful way to understand where the money actually goes.
The practical answer is to treat conversion as a cost you control rather than a detail you discover later. A route that discloses its exchange rate before confirmation, keeps the number of conversions to one, and delivers directly into the beneficiary bank account removes the gap entirely, and that is the standard worth measuring every provider against.
Four Checkout Models Compared
Different stores need different setups. The table below sets out the main options.
| Model | How it works | Best suited to |
|---|---|---|
| Single currency, single method | Everything priced and charged in one currency | Very early stores testing one overseas market |
| Local currency display | Prices converted for display, charged in your currency | Stores that want a quick conversion lift |
| Local currency pricing | Prices set and charged in the shopper's currency | Stores with real volume in several markets |
| Local currency plus local methods | Local prices, local methods, local acquiring where available | Established cross-border sellers |
The trade-off is margin against conversion. Every step towards the bottom of that table costs more to operate and converts better. The right answer depends on how much of your revenue already comes from outside your home market.
Choosing a Payment Service Provider for Cross-Border Sales
A payment service provider is not just a way to accept cards. For a cross-border store, it is the infrastructure that decides which currencies you can hold, which payment methods you can offer, and how much of the exchange rate spread you keep or lose.
When comparing providers, ask five questions.
- Which currencies can I price in, and which can I settle in?
- Which local payment methods are supported in each target market?
- Is the exchange rate applied at the moment of the transaction or at settlement?
- What are the cross-border and currency conversion fees, stated as a percentage?
- How are refunds, chargebacks, and partial refunds handled across currencies?
Most providers publish the headline transaction fee prominently and the conversion detail quietly. The conversion is usually the larger cost.
The Costs That Hide in Cross-Border Checkout
Cross-border checkout costs arrive in layers, and only one of them is the fee you were quoted.
- Transaction fee. A percentage of the order value, sometimes with a fixed component.
- Currency conversion spread. The difference between the rate applied and the mid-market rate.
- Cross-border assessment. A fee applied by card networks when the issuer and acquirer sit in different countries.
- Payout fees. Charged when your balance is settled into your bank account.
- Refund handling. Some providers do not return the original conversion cost when an order is refunded.
- Chargeback exposure. Higher in markets where cardholder protection is strong and delivery is slow.
A store that quotes a two percent fee and applies a three percent spread is not a two percent store. It is a five percent store with a better headline.
How to Set Up Multi-Currency Checkout Step by Step
The sequence below keeps the project manageable and avoids the usual rebuild later.
- Decide your pricing currency. Choose the base currency you will hold prices in and the currencies you will display. Base it on where your buyers actually are, not where you would like them to be.
- Set a conversion policy. Decide whether you absorb the spread, pass it to the buyer, or split it. Write the rule down so the store does not apply three different approaches across three pages.
- Configure rounding and psychology. Local rounding matters. A price that reads awkwardly in a currency signals an imported store.
- Choose payment methods per market. Cards dominate in some markets, while bank transfer and direct account based methods dominate in others. Offer what buyers in each market actually use.
- Test real transactions. Run a live test payment in every currency you enable, then check what actually settled into your account against what the customer paid.
- Display duties and taxes clearly. Unexpected charges on arrival cause disputes and chargebacks. Clear landed cost messaging reduces both.
- Review the settlement report monthly. Compare the rate promised at checkout with the rate settled. Adjust or change providers when the gap widens.
Where a Modern Payment Platform Fits Into a Cross-Border Operation
Checkout solves the money coming in. The other half of a cross-border store is the money going out, and that half is where margin quietly disappears.
A store selling internationally pays overseas suppliers, freight forwarders, advertising platforms, packaging vendors, and often a remote team. Each of those payments crosses a border, and each one can pick up a bank fee, a conversion spread, and a delay that holds up the next shipment.
DapsyPay is built for that outbound side. Payments run on conventional international transfer rails such as SEPA and ACH, the exchange rate and the full fee are shown before you commit, and the money is delivered directly into the beneficiary bank account. There are no limits that force a large supplier payment to be split across several days, which matters when you are paying for bulk stock or settling several vendors in the same week. The platform is designed for business owners and bulk sending rather than for occasional one-off transfers.
For sellers running a full import and resale cycle, our guides to paying international contractors and how cross-border transfers work explain how to structure the outgoing side. Sellers building an outbound payments process from another market will also find our guide to sending money abroad from India useful, and readers who want a separate view on transaction costs and account safety will find one in our guide to fees, spreads and safety.
Common Mistakes That Break Cross-Border Checkout
- Converting for display only. The customer sees one number and their bank charges another.
- Ignoring local payment methods. Card only is a conversion ceiling in many markets.
- Not testing with a real foreign card. Sandbox tests hide issuer declines and address mismatches.
- Rounding badly. Awkward local prices reduce trust in the whole store.
- Forgetting the return leg. Refunds across currencies can cost more than the original sale.
- Treating the exchange rate as a detail. The spread is usually the largest single cost in a cross-border order.
- Paying suppliers on an ad hoc basis. Unplanned outbound transfers create delays that show up as late deliveries.
Frequently Asked Questions
Conclusion
Multi-currency checkout is a commercial decision wrapped in a configuration task. Showing local prices and local payment methods removes doubt from the payment step, and removing doubt is what lifts conversion.
The part most stores get wrong is the second half of the cycle. Money that arrives at a good rate and leaves at a bad one produces thin margins and confusing reports. Getting both directions of a cross-border business onto predictable rails, with the exchange rate and fees visible before commitment, is what turns international selling from a gamble into a process.
Pay Suppliers Abroad Without the Guesswork
See the exchange rate and the full fee before you confirm, and send straight into the beneficiary bank account on fast conventional rails.
Visit dapsypay.com