
How to Send Money Abroad from India: Methods, Costs and Timelines
To send money abroad from India, you normally use an authorised dealer bank, a full-fledged money changer, or an online transfer service that works with both. Transfers fall under the Liberalised Remittance Scheme, which allows up to 250,000 US dollars per financial year per individual for permitted purposes. You will need identity documents, a purpose code, and often a tax declaration. Costs come from three places: the bank or service fee, the exchange rate margin, and any withholding on certain purposes. Bank wires are reliable but slow and expensive. Online services are faster and cheaper but have their own limits.
How Outward Remittance from India Actually Works
Sending money out of India is regulated, and the rules shape every method available.
The Liberalised Remittance Scheme, administered by the Reserve Bank of India, allows resident individuals to remit up to 250,000 US dollars per financial year for permitted current and capital account purposes. Education, medical treatment, family maintenance, travel, gifts, and investment in certain overseas assets all fall within it. The Reserve Bank of India publishes the scheme rules, the permitted purposes, and the documentation requirements that banks must follow, which is why the same transfer can require different paperwork depending on how it is described on the form.
Two consequences follow from that framework. First, the purpose you declare determines the documentation. Second, the institution you use must be authorised to handle outward remittance. That is why a payment that looks simple on paper can take several days of paperwork before any money moves.
The Main Ways to Send Money Abroad from India
There is no single best method. Each one fits a different amount, purpose, and timeline.
| Method | Typical speed | Cost profile | Best for |
|---|---|---|---|
| Bank wire through an authorised dealer | Two to five business days | Fixed fee plus exchange margin plus GST | Large amounts, formal purposes, property and education payments |
| Online transfer service | Often one to two business days | Lower fixed fee, margin built into the rate | Regular medium-sized transfers |
| Full-fledged money changer | One to three business days | Cash handling and margin | Smaller transfers, travel money |
| Forex card or prepaid instrument | Loaded in advance | Load fee plus conversion margin | Travel spending rather than transfers |
| Bank card payment | Varies | Highest effective cost on foreign currency | Small, one-off payments |
Bank wires remain the default for anything formal. They are also the slowest and the least transparent on price, because the exchange margin is rarely disclosed as a separate line. Online services such as Wise show the conversion rate and fee upfront, which is a real improvement on the traditional model, though limits and supported purposes vary by corridor. Remitly publishes clear delivery estimates per corridor, which is useful when a deadline matters more than the last few basis points. Both are a genuine improvement on a traditional bank wire, though the transfer can still pass through a chain of intermediaries, and each hop is a place where a charge can be deducted.
The route that avoids that accumulation is the one that matters when you compare providers. Conventional rails such as SEPA and ACH, a disclosed exchange rate and fee before you confirm, and delivery directly into the beneficiary bank account remove the deduction problem, and no limit forces a large payment to be split across several days.
What It Actually Costs
The advertised fee is the smallest part of the cost. Three components matter.
The service fee. Banks charge a fixed amount per transaction, often with a percentage component for larger sums. Online services usually charge a lower percentage plus a small fixed fee.
The exchange rate margin. This is the gap between the mid-market rate and the rate applied to your transfer. It is expressed as a percentage, and on large transfers it dwarfs every other charge. A one percent margin on a 50,000 dollar transfer is 500 dollars, many times the visible fee.
Tax treatment. Certain purposes attract tax collected at source above defined thresholds, and the rate depends on the purpose and the amount. The thresholds and rates change, so confirm the current position with your bank or a tax adviser before you initiate a large transfer.
Rates also attract GST on the service component. None of this appears in a headline comparison, which is why total cost, expressed as a percentage of the amount sent, is the only number worth comparing.
How Long Transfers Take
Timelines depend on the method and the purpose, not on the amount alone.
- Online services: often one to two business days once documents are accepted.
- Bank wires: typically two to five business days, longer if a correspondent bank raises a query.
- Forex dealers: one to three business days.
- Documentation reviews: can add a day or more, particularly for education and property payments where supporting papers are checked.
Cut-off times matter. A payment submitted after the bank's daily cut-off starts the next business day, and each intermediary in the chain has its own cut-off. A transfer that looks like it should take two days can take four without anything going wrong.
Documents You Will Need
Requirements vary by bank and purpose, but the core set is consistent.
- A valid passport and PAN
- Proof of address
- A completed remittance application with the purpose code
- The beneficiary's bank details, including the account number, the bank's address, and any intermediary bank details
- Supporting documents for the purpose, such as an admission letter, a hospital estimate, an invoice, or a property agreement
- A tax declaration where the purpose or amount requires it
Errors in beneficiary details are the most common cause of a delayed or returned payment. Matching the account name exactly, as it appears on the beneficiary's bank record, prevents most of them.
Choosing the Right Method
Work through the following before you initiate anything.
- Confirm the purpose is permitted under the current scheme rules.
- Check your annual headroom. The yearly limit applies across all your transfers.
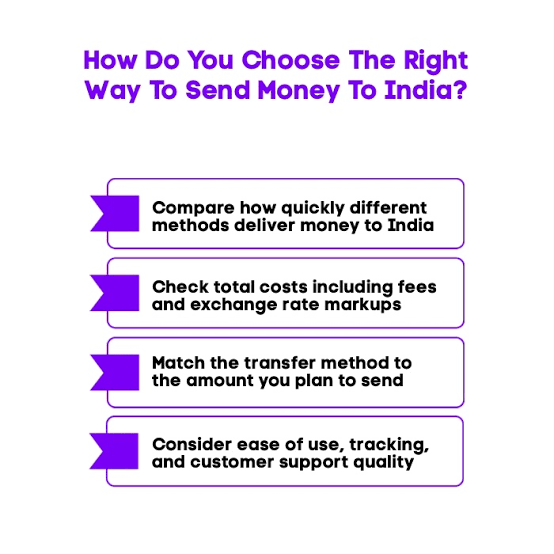
- Calculate the all-in cost as a percentage of the amount sent, not as a flat fee.
- Check the delivery date against your deadline, and add a buffer for documentation review.
- Ask who absorbs intermediary charges. Some instructions allow deductions along the chain, which reduces what arrives.
- Keep the payment reference. It is the only way to trace a payment that stalls.
Where a Modern Payment Platform Fits
For anyone paying abroad regularly, whether that is tuition in several instalments, hospital deposits, supplier invoices, or contractors, the recurring problem is not a single transfer. It is the second, third, and tenth transfer, each carrying its own charges and each taking its own time.
DapsyPay is built for that pattern. Payments run on conventional international transfer rails such as SEPA and ACH rather than through a chain of intermediaries, the exchange rate and the full fee are shown before you commit, and the money is delivered directly into the beneficiary bank account. There are no limits that break a large payment into several days, which makes the platform practical for bulk sending and for business owners paying several recipients in the same month. Instead of reconciling a different charge on every transfer, you see the same transparent structure each time.
For readers working through the paperwork itself, our guide to how cross-border transfers work explains what happens after you submit a payment. Businesses sending payments to overseas freelancers and agencies will find our guide to paying international contractors useful, and sellers collecting money from overseas buyers should read how to add multi-currency checkout. Readers who want a separate view on transaction costs and account safety will find one in our guide to fees, spreads and safety.
Common Mistakes
- Comparing flat fees only. The exchange margin is usually the larger cost.
- Leaving documentation until the deadline. Reviews add days.
- Ignoring the annual limit. It applies across all your transfers in the financial year.
- Using a card for a large payment. Card conversion is the most expensive route on foreign currency.
- Not checking beneficiary details. A single character error can return the payment days later.
- Assuming the recipient receives the full amount. Intermediary deductions reduce the arrival value.
- Splitting a transfer to dodge documentation. It creates more paperwork, not less.
Frequently Asked Questions
Conclusion
Sending money abroad from India is a documented process with a known set of steps: confirm the purpose, prepare the papers, compare the all-in cost rather than the headline fee, and give yourself a buffer on timing.
The method matters less than the structure. A route with fewer intermediaries, a disclosed exchange rate, and direct delivery into the beneficiary bank account is predictable, and predictability is what makes recurring payments manageable rather than stressful.
Send Money Abroad With Costs You Can See
Transparent rates, fast conventional rails, and delivery straight into the beneficiary bank account, with no limits on bulk sending.
Visit dapsypay.com